HEIBERG ESTATES NEWSLETTER: OCTOBER 2026
Dear Property Partners
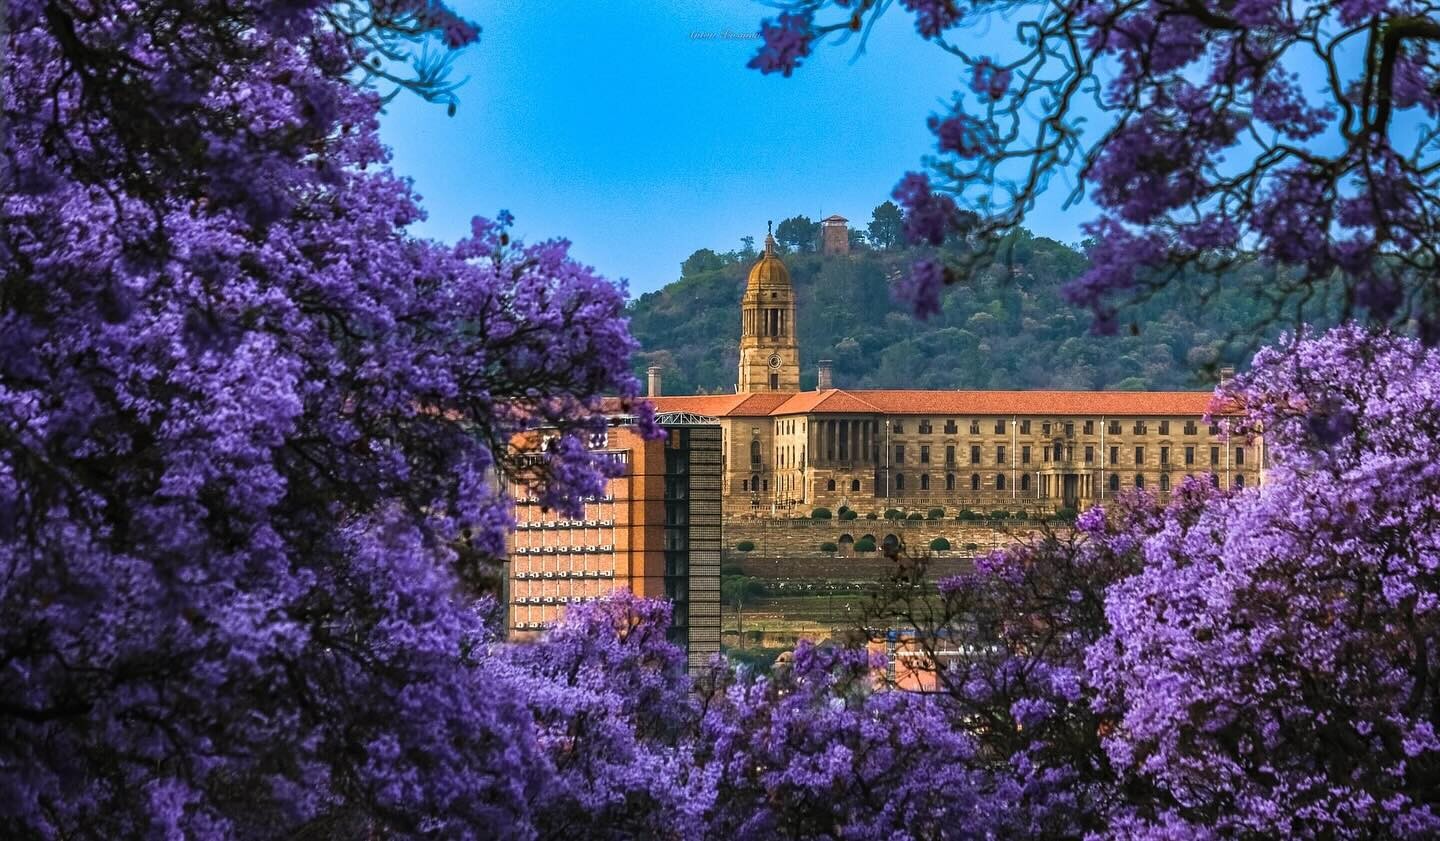
Warm greetings from our beautiful Jacaranda City, adorned in magnificent colour and celebrating the splendour of full bloom!
As we gain momentum towards year-end, both encouraging and challenging trends are emerging across the South African property market. Although national house price growth has been positive, recent indications suggest a renewed moderation, with September’s interest rate increase and persistently rising fuel prices placing noticeable pressure on affordability, property values and sales volumes. Our property market may well have reached its peak for 2026, with approved bond applications declining and the South African Reserve Bank recently confirming that growth in the value of new residential mortgage loans granted has moderated from its peak in late 2025. Adding to these concerns are renewed and alarming fuel price increases, their far-reaching inflationary effects across our fragile economy, ongoing global political and economic uncertainty surrounding the Middle East conflict, and the possibility of another interest rate increase before year-end. Statistics South Africa reports that September inflation edged upwards by 0.1 percentage points to 4.5% year-on-year, compared with 4.3% in July. Global inflationary pressures continue to influence our interest rate outlook, particularly as the ongoing Middle East conflict shows little indication of an imminent resolution.
Leading economist John Loos highlights that year-on-year growth in the value of new residential mortgage loans granted reached 18.2% during the third quarter of last year, before moderating to 9.54% for the three months to July 2026. The implications of May’s initial interest rate increase, followed by a further 25-basis-point adjustment last month, should not be underestimated when considering the market’s near-term prospects. Buyers are also encountering higher deposit requirements, although conditions remain more favourable than two years ago, with overall deposit requirements still 7.3% below their 2024 levels. Lending criteria have likewise become more stringent.
Mr Loos further emphasises that, without the Western Cape property market’s exceptional and sustained performance, South Africa’s longer-term property landscape would present a markedly different picture. Since 2010, average national house prices have remained broadly unchanged in real terms, with nominal growth generally confined to lower single digits. In contrast, the Western Cape has been the principal contributor to real residential property appreciation nationally, achieving impressive real house price growth exceeding 35% since 2010. The province continues to distinguish itself as the country’s leading performer, recording year-on-year growth of 11.2% in May, compared with Gauteng’s 5.5% and KwaZulu-Natal’s 4.5%. Even more remarkably, average Western Cape house prices have appreciated by 197.8% since 2010, compared with 85% in Gauteng and 81.1% in KwaZulu-Natal.
Encouragingly, leading economists anticipate the possibility of credit rating upgrades by major international rating agencies towards year-end or early next year. A sovereign credit rating independently assesses a government’s creditworthiness, and South Africa’s current speculative-grade status remains two notches below investment grade. Moody’s Ratings and S&P Global Ratings are scheduled to review their assessments in November, followed by Fitch Ratings in December. An upward adjustment, potentially towards Ba1 or BB+, would represent a welcome improvement in our international investment standing and could pave the way towards regaining investment-grade status during 2027. Such progress could strengthen investor confidence, encourage foreign capital inflows, stimulate international trade and provide much-needed momentum for our fragile economy and sustainable employment creation. These developments would, in turn, enhance the prospects for our property market, supporting stronger transaction volumes and renewed house price appreciation.
Some additional noteworthy facts and statistics are as follows:
- Recent BetterBond data indicates that the average price paid by first-time buyers has increased by 8% year-on-year, with the average first-time buyer property now costing R1.4 million — a nominal increase of 19% compared with the third quarter three years ago. Nationally, average house prices increased by 5.9% over the past year, compared with just 1.2% during the preceding 12-month period. Persistent stock shortages across all price categories continue to underpin this positive price growth.
- The strongest-performing buyer segment comprises households earning below R15 000 per month, where average house prices increased by 8.8% over the past year. This was followed by buyers earning between R15 000 and R25 000 monthly, whose segment recorded growth of 6.5%. The highest-income category, earning above R55 000 per month, moved from second to third position. Notably, house price appreciation across all three income categories has exceeded the prevailing inflation rate.
- Regional dynamics are playing an increasingly significant role in our residential property market, particularly in areas offering sustainable employment opportunities, reputable schools and universities, and reliable municipal services. The Western Cape remains the standout performer, followed by Greater Pretoria, with both regions achieving double-digit house price growth over the past 12 months. Average Western Cape prices increased by 13.8%, while Greater Pretoria/Gauteng recorded growth of 11.5%. Pretoria continues to benefit from its position as South Africa’s administrative capital, accommodating government departments, numerous foreign embassies, corporate institutions and other major employers that sustain residential demand.
- BetterBond further confirms the resilience of our property market, with home loan applications remaining above 2023 levels. Encouragingly, the relationship between household incomes and property prices has improved across most market segments, while the home loan approval ratio has strengthened to 64.5%.
- Notably, following last month’s interest rate increase, which brought the prime lending rate to 10.75%, the value of new residential mortgage loans granted has moderated, consistent with the customary response to higher borrowing costs. SARB data reflects a slowdown in year-on-year growth from its previous peak of 18.2% to 9.54%.
While there is no reason for undue pessimism, a realistic perspective suggests that the final quarter of 2026 will prove more challenging for our property market than the preceding three quarters. Persistent economic pressures, particularly the gradual upward movement in inflation and escalating fuel prices, continue to create a ripple effect throughout our economy, constraining sustainable employment growth. These factors inevitably influence consumers’ confidence and capacity to invest in property, particularly as disposable household income comes under increasing pressure. There are growing calls for government to address the underlying causes of our economic difficulties, notably corruption and unemployment, rather than concentrating predominantly on short-term crisis management and economic survival.
Already, South Africa’s initial economic growth forecast of approximately 1.6% for 2026 has been revised downwards to 1.2%, a level unlikely to reverse the country’s persistently high unemployment rate. Economic growth over the past decade has remained disappointingly subdued, while several countries confronting comparable challenges have achieved growth approaching 4%, against a global average of approximately 3%.
South Africa’s GDP contracted during the previous quarter for the first time in six consecutive quarters, while investment declined to 13.6% of GDP during the second quarter. Nevertheless, the anticipated sovereign credit rating improvements mentioned earlier, potentially before year-end, could provide a welcome catalyst for renewed foreign investment. Such capital inflows would contribute towards strengthening economic activity, stimulating employment opportunities and restoring confidence in our country’s longer-term growth prospects.
It is also important to recognise that, over recent years, South Africa has benefited from a relatively favourable, stable and supportive bank lending environment. This has helped sustain property market activity, encouraging moderate growth in both transaction volumes and selling prices. With buyer demand consistently exceeding available supply in several market segments, the underlying fundamentals of our residential property market remain reassuringly sound, providing a valuable foundation for continued resilience and future growth.
With the end of the year already looming, don’t hesitate to call your Heiberg Estates Team whether you want to sell, rent or buy! It is always a pleasure to be 24/7 there for you, please call us!
With our very best regards
Yours truly
Bambie & Heiberg Estates Team